You can already picture it. Morning coffee overlooking the water. A kayak waiting by the shoreline. Summer weekends that begin with a walk to your own dock.
Then you start looking at lakefront listings and wonder: How do I make this happen without stretching my budget too far?
Saving money on your first lake house starts well before you make an offer. The lake you choose, the features you prioritize, and the questions you ask can all affect what you spend at closing and for years afterward.
Here are practical ways to make your lake house budget go further.
1. Shop for Your Lifestyle First
Before falling in love with a particular lake, think about how you will actually use the water.
Will you spend weekends kayaking and swimming? Do you need a lake that allows waterskiing? Is fishing your priority? Would a peaceful setting suit you better than a busy boating destination?
If you prefer paddling and quiet evenings, broadening your search to lakes with motor restrictions may uncover properties you would otherwise overlook.
Likewise, paying for a large boating lake makes more sense when you plan to use it.
Write down your three most important lake activities. Let those guide your search before the kitchen finishes do.
2. Expand Your Search Beyond the Famous Lakes
A well-known lake can attract buyers who begin their search with that name alone. Nearby alternatives deserve a closer look.
Explore smaller lakes, less familiar communities, and locations slightly farther from major highways or resort centers. Compare actual listings and recent sales to see where your budget buys more.
Keep travel time in the equation, though. A less expensive home that you rarely visit may deliver less value than a slightly pricier property you use every weekend.
The goal is an affordable lake house that fits your life well enough to enjoy regularly.
3. Look Past Cosmetic Problems
Dated wallpaper, worn carpeting, and an unfashionable bathroom can make a good lake house easy to dismiss.
They can also create an opportunity.
Separate improvements you can complete gradually from expensive problems that need immediate attention. Paint and lighting belong in a different category from foundation repairs, a failing septic system, or shoreline instability.
Focus on the setting, layout, structural condition, and water access. Then get realistic estimates for the work.
A home with cosmetic flaws may offer value, but only when the purchase price leaves enough room for improvements.
4. Budget for the Whole Property
The mortgage payment is only part of the cost of owning a lake house.
Before making an offer, investigate property taxes, insurance, heating, association dues, private road expenses, dock maintenance, and seasonal services. Ask for available bills and records rather than relying on a general estimate.
Get insurance quotes early, including a separate flood insurance quote when appropriate. Standard homeowners insurance generally does not cover flood damage.
For illustration, an additional $400 per month in ownership expenses adds up to $4,800 annually. Understanding those costs helps you compare homes on a more useful basis than asking price alone.
5. Spend Wisely on Inspections
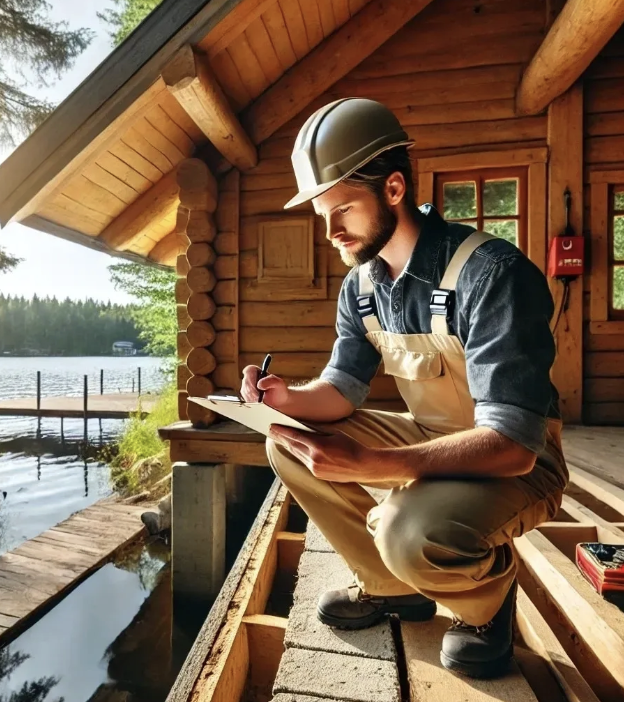
An inspection is an upfront expense that can help you understand the financial commitment you are making.
For a lakefront property, ask your inspector and agent which additional specialists may be appropriate. Depending on the home, that could include septic, well, structural, or waterfront expertise.
The EPA recommends having a septic system inspected before purchasing a home that uses one. Request maintenance records and clarify what the inspection covers.
Have qualified professionals help verify waterfront boundaries, access rights, and relevant dock approvals, too.
Discovering a problem before closing gives you time to evaluate repair estimates, negotiate where appropriate, or reconsider the purchase.
6. Compare Mortgage Offers Carefully
Give your financing the same attention you give the property.
Request Loan Estimates from multiple lenders using comparable loan amounts, loan types, and timing. Compare rates, lender fees, points, closing costs, and monthly payments. The Consumer Financial Protection Bureau provides guidance for making these comparisons.
Tell each lender how you intend to use the home and whether it is seasonal or suitable for year-round occupancy.
Your first lake house could be your primary residence, a second home, or an investment property. Make sure the financing discussion reflects your actual plans.
Ask questions until you understand both the upfront cost and the ongoing commitment.
7. Negotiate Around the Seller’s Priorities
Price matters, but a productive negotiation can involve more than a lower number.
A seller may value a flexible closing date or extra time to organize a move. You may value a credit toward allowable closing costs or having useful furnishings included.
A lawn mower, outdoor furniture, or dock equipment could reduce your initial shopping list. Confirm ownership, condition, and what is included in writing. Have your agent and lender explain how personal property should be handled.
Look for terms that serve both parties while keeping your inspection and due diligence needs in focus.
8. Watch Timing Without Expecting a Guaranteed Bargain
Keep an eye on homes that have been available for a while, returned to the market, or received price reductions.
Ask why.
The answer could involve condition, pricing, access, or circumstances unrelated to the property. Longer market time provides a reason to investigate, rather than proof of a bargain.
Fall and winter searches may also reveal opportunities, depending on the local market. If snow, ice, or a seasonal drawdown limits what you can inspect, arrange the additional due diligence needed to understand the waterfront.
Compare recent sales and the property’s condition before deciding what to offer.
9. Buy What You Need for Your First Season
It is easy to furnish a lake house for every gathering you imagine hosting.
Start with how you will use it most often. A smaller home with comfortable everyday space may fit your budget better than extra bedrooms used only occasionally.
Apply the same thinking to boats, renovations, and equipment. Spend a season learning the property before committing to major discretionary purchases.
Keep a reserve for repairs and unexpected expenses. Having money available after closing makes it easier to enjoy the home with confidence.
Make Your First Lake House a Smart Purchase
The best value comes from matching the right property to your lifestyle and understanding its costs before you commit.
Be flexible about finishes. Be thorough about condition, access, and ownership expenses. Work with a local lakefront specialist who can help you ask questions specific to the lake and property.
Ready to explore your options? Visit LakefrontLiving.com to search direct lakefront homes and connect with a local lakefront specialist. Your first lake house may be closer to your budget than you think.
Posted by Scott Freerksen “The Lake Guy”